Originally published by valorinternational.globo.com.
Brazil’s tax authorities are preparing to shield companies from penalties for honest mistakes as the country moves ahead with a sweeping consumption-tax overhaul, despite concerns that many businesses are not ready for the new system.
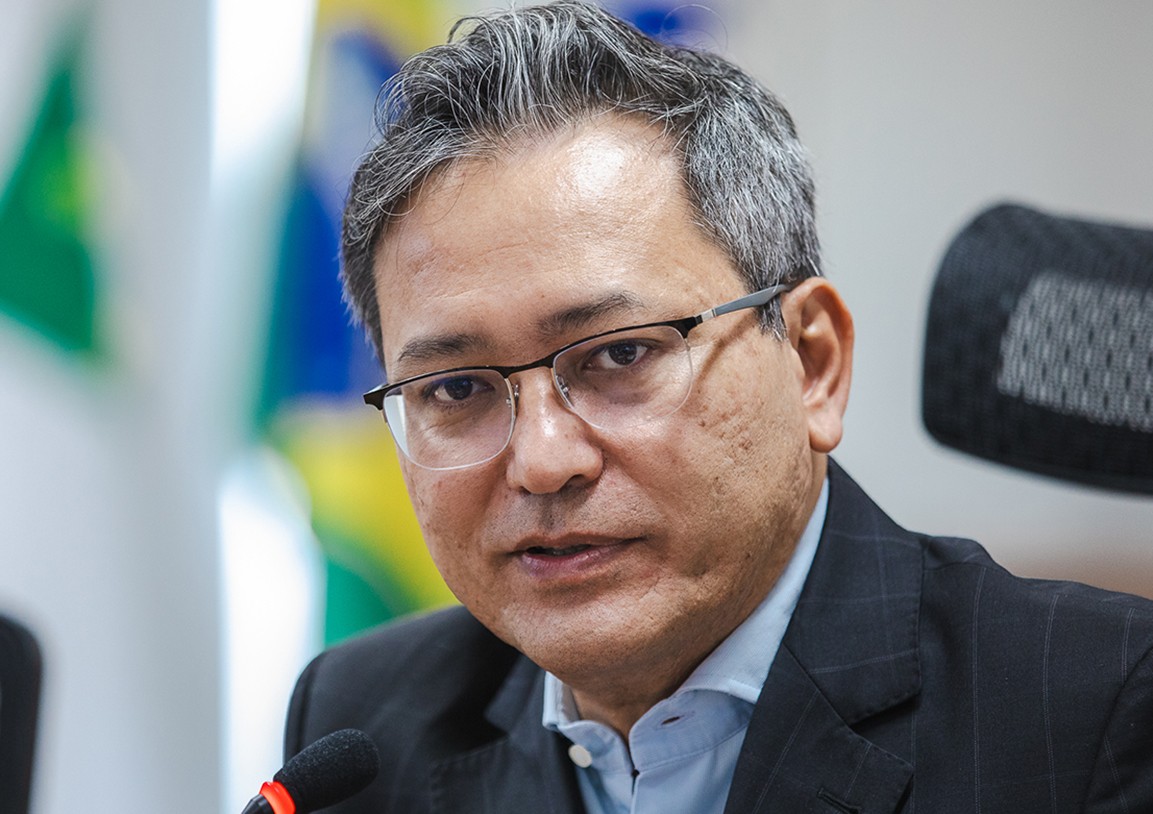
Federal Revenue Secretary Robinson Barreirinhas said a compliance program would be announced soon, with the presumption that taxpayers are acting in good faith unless authorities find evidence to the contrary. The government has ruled out postponing the reform, which is scheduled to enter a new implementation phase in January 2027.
- Pending issues with tax reform are fueling business worries
- Curbing tax breaks could tackle economic and wealth distortions, experts say
Barreirinhas made the remarks during the first livestream of Observatório Tributário, a Valor initiative designed to keep readers informed about discussions surrounding the rollout and implementation of Brazil’s tax reform.
The program, eagerly awaited by taxpayers concerned about the transition, will protect companies that make mistakes without deliberately violating tax rules. The authorities will generally presume that taxpayers are acting in good faith, Barreirinhas said.
“Bad faith is the exception, and it is what must be proven,” he said. Evidence could include withholding information, concealing taxable transactions or other attempts to disguise activities subject to taxation.
“Naturally, [the program] is something that will become permanent, but the text we are currently working on is intended, at least initially, for 2027,” he said.
The secretary acknowledged that not all companies are ready to operate under the new tax system. This situation has prompted calls for a postponement. He ruled out any delay.
“We receive these expressions of concern, and even fear, I would say, with great humility and respect. But our role as the tax administration is to provide as much transparency as possible, guide taxpayers and reassure them that Brazil will be ready for tax reform,” he said.
The Federal Revenue Service has already identified companies that are failing to include the new federal Contribution on Goods and Services (CBS) on their invoices and is working to guide them toward compliance. “It is an area of concern,” Barreirinhas acknowledged.
Companies that fail to issue invoices correctly will create additional work for their customers, who will have to report the tax amounts themselves through the new system of prefilled tax assessments, known as assisted assessment. For that reason, the secretary expects businesses to correct their procedures.
Another major outstanding issue is the second version of the regulations governing the CBS and the Tax on Goods and Services (IBS), the state and municipal component of the new consumption-tax system. The revised rules are expected to be released by early next week at the latest.
The update addresses provisions that have generated significant uncertainty in sectors including finance, construction and services. Because further suggestions for improvements are expected, Barreirinhas said the regulations will remain subject to ongoing revisions.
The secretary also sought to clarify the relationship between tax reform and the government’s fiscal adjustment bill, which the Senate approved on Wednesday.
According to Barreirinhas, restrictions on the use of tax credits under the fiscal package will not apply to the new consumption-tax system. In particular, credits accumulated under the existing PIS and Cofins federal contributions will not face additional restrictions when offset against the CBS during the transition.
Regarding the CBS reference rate of 11.3%, calculated by Brazil’s federal spending watchdog, the Federal Court of Accounts (TCU), and under consideration in the Senate, Barreirinhas noted that tax exemptions and preferential treatment for some taxpayers ultimately impose costs on others. “If you want to reduce [the rate], you can, but then you also have to reduce a particular tax benefit,” he said.
Below are the main excerpts from the interview.
Compliance program
Companies won’t stop doing business, selling goods, or providing services because of tax reform. What matters is that they continue operating with confidence and with a high degree of transparency in their relationship with the tax authorities.
The 2027 compliance program will be announced very soon. As far as the Federal Revenue Service is concerned, it is already quite advanced.
I ask for the public’s understanding. This program involves the Federal Revenue Service, 26 states, the Federal District, and 5,557 municipalities. That creates a need for governance and for bringing everyone on board so that the program is uniform.
This compliance program has a very important reassuring function for businesses, perhaps even more important than its actual application.
Tax reform is an opportunity to change the culture of the relationship between the tax authorities and taxpayers, moving toward guidance and mutual trust.
I believe this will naturally become permanent. The year 2027 will also be a learning period. Throughout the year, we will see what works better or worse and make adjustments afterward.
Naturally, it will become permanent, but the text we are currently working on is intended, at least initially, for 2027.
Good-faith errors and deliberate violations
Good faith is the rule. Bad faith is the exception, and it must be proven.
In principle, taxpayers are acting in good faith unless there are indications of bad faith.
For example, withholding information, disguising a taxable event, deliberately concealing a taxable transaction, a sale, or the provision of a service.
If there are no such signs of bad faith, I have to start from the assumption that the company is acting in good faith.
We will have even more objective criteria for situations in which there is significant uncertainty about how a rule should be interpreted.
Updated tax regulations
They should be released by Friday. We are pushing for that.
The ball is now in our court. The Management Committee has already approved the regulations, and they are now moving through the relevant departments within the federal government. They should be released this week or, at the latest, next week.
The good news is that they will be released.
The news that may sound bad to some people is that this process will never really end. It is an ongoing process.
We received more than 4,000 suggestions for changes. We analyzed all of them, but at this initial stage we accepted those that seemed most critical.
Naturally, we will continue making adjustments over time.
We addressed critical issues affecting several sectors, including financial services, construction, and certain other services, where we identified significant uncertainties.
The solution to this kind of uncertainty among taxpayers is not necessarily to change the regulations.
How do you resolve something that may appear to be a regulatory gap? Through interpretation, using our compliance program and a system of questions and answers agreed upon with the Management Committee.
Many issues do not require changes to the rules. It is enough to guide taxpayers.
Fiscal adjustment and tax reform
I want to reassure everyone that the fiscal adjustment proposal does not apply to tax reform.
The text is very clear that the restriction on the use of credits concerns offsets between taxes administered by the Federal Revenue Service and other types of federal taxes, as provided in Article 74 of Law 9,430, if I am not mistaken.
That is a general federal provision allowing, for example, credits from a contribution to be offset against income tax liabilities.
Offsetting PIS/Cofins credits against the CBS under the non-cumulative taxation system established by Supplementary Law 214 is not the offsetting mechanism covered by Article 74.
Therefore, this legislative proposal does not apply to PIS/Cofins credits used against the CBS during the transition, much less to CBS credits offset against CBS liabilities, which involve the same tax.
To be clear, it does not interfere with the transition to the new tax system or the non-cumulative taxation mechanism established by the reform.
Other restrictions on tax credits
In other situations, the measure reduces the scope for offsetting tax credits. It does not prevent offsets. It restricts them. In fact, this situation comes close to a tax benefit.
The clearest example is when no tax is charged on the sale of a product or service, but substantial presumed tax credits are granted on inputs. This happens frequently under PIS/Cofins. In that situation, the presumed credit exists even though no tax is due on the sale. That is effectively a benefit.
The objective is to limit the amount of this type of credit that can be used over time to just 10%.
Reducing the federal consumption-tax rate
Congress has the final say on the tax rate, but the Constitution and the supplementary law are also very clear. And that is the beauty of tax reform: transparency.
We now know, clearly, that any reduction or benefit granted to one taxpayer is paid for by someone else.
The calculation methodology presented by the Federal Revenue Service, validated by the TCU, and the TCU’s own calculations allow any scenario to be simulated. If you want to reduce the rate, you can. But then you also have to reduce a particular tax benefit.
Gains from improved tax compliance
Some senators are proposing a reassessment of the expected gains from improved tax compliance. That is also possible.
Sometimes the gains from compliance—an increase in taxpayers voluntarily meeting their obligations—and the reduction in tax evasion are greater than the TCU estimated. But we will only know that during 2027, when the system is operating.
Naturally, any such gains will be reflected in the following year’s rate, because we also have a transition period through 2032 involving the tax rate. This reference rate applies only to next year. Next year, we will redo the calculation with more information.
Coordination with the state and municipal tax committee
We have been discussing how to provide taxpayers with predictability and legal certainty through a compliance program. We will issue a detailed statement.
The members of the Management Committee still need to incorporate the meeting’s outcome into their procedures.
But I can say in advance that the meeting was entirely focused on aligning everyone behind the principle of recognizing the good faith of compliant taxpayers and placing guidance at the center of the relationship between the tax administration and businesses.
Official tax calculator and protection from penalties
Linking tax credits to actual payment means that, as split payment develops, this process will become automated, eliminating the compliance problem.
The Federal Revenue Service’s tax calculator is very important in this regard. As the name suggests, it is a software module that we have developed and made available to information technology companies. What are we telling software developers? Use our calculator, and you won’t make mistakes.
When you enter a service description and its code, our system identifies the correct classification and tax rate. It calculates the tax exactly as the Federal Revenue Service would during an audit. That virtually eliminates compliance costs.
We are even considering exempting users of our calculator from audits and penalties related to calculation errors. The calculator has been available for months, and we encourage IT companies to use it.
Tax evasion and future rates
In 2027, the Federal Revenue Service will submit a new calculation methodology, incorporating new data from the period. The TCU will then be able to fine-tune the tax rate using actual CBS revenue data, including information on reductions in tax evasion. That will automatically feed into the following year’s rate, either up or down.
The TCU made a series of estimates, and so did the Federal Revenue Service. If we were too optimistic, the rate could move upward. If we were too pessimistic, it could move downward.
That is why lawmakers wisely provided for annual reviews of these rates, so that by the end of the transition period in 2032 we will have a rate refined over the entire period, allowing us to maintain the overall tax burden more accurately.
Split payment and automatic tax collection
Split payment is not a problem. It is a solution to tax evasion and, therefore, to the high tax burden borne by those who actually pay their taxes. As the systems evolve, split payment will become mandatory. That depends much more on the systems financial institutions use than on the Federal Revenue Service. We are ready for split payment.
Simplifying tax reporting
Another enormous gain in reducing compliance costs is reducing tax returns and, eventually, eliminating them. In the future, the taxpayer’s only obligation will be to issue the tax document.
Under assisted assessment, in addition to entering the relevant information, I will calculate the credits, liabilities, and offsets, and provide the federal tax payment slip at the end.
Previously, depending on the size of the company, you needed an entire department to do that. That will no longer be necessary. You will simply need to issue the document correctly, and I will automatically provide the tax assessment.
Cash-flow concerns and buyer-administered tax payments
We are advising companies not to take any risks. They should use the buyer-administered tax payment mechanism, known as RAD (Recolhimento pelo Adquirente).
On January 10, I will make a purchase from a supplier, withhold the CBS amount at source, and remit it on the supplier’s behalf. That requires a discussion between the two parties. They will have to agree to the withholding and payment process. If companies do this work now, toward the end of the year, talk to their suppliers and adopt RAD, the problem disappears.
So that is Plan A. We want everyone to do this. Plan B is to provide some breathing room by postponing payment until the following month. But even Plan B does not fully solve the problem. To solve it, companies should use RAD. Over time, these issues will be resolved.
Obviously, the buyer will contact the supplier. When the supplier subsequently pays the tax, even if late, we will recognize the corresponding credit in the buyer’s assisted assessment. Over the following months, the situation will be resolved.
However, companies need to be very careful at the beginning, during the transition from the current system involving the federal tax on manufactured products (IPI) to a system in which tax credits are linked to actual payment.
Tax rebates for low-income households
The cashback system will start operating immediately. It will cover beneficiaries registered in CadÚnico, Brazil’s federal registry of low-income households. They will receive at least 20% of the CBS they have paid back into their accounts.
We are making arrangements for these payments to be made through Caixa Econômica Federal, the state-owned bank that holds accounts for most of these beneficiaries. For certain services, the cashback rate will be 100%. Refunds will be made quarterly through Caixa. The first payment will take place in April 2027.
This article was translated from Valor Econômico using an artificial intelligence tool under the supervision of the Valor International editorial team to ensure accuracy, clarity, and adherence to our editorial standards. Read our Editorial Principles.
Mais recente Próxima Central Bank director defends capital requirements increase for fintechs