Navigating Ups and Downs in the Automotive Supplier Industry - Bain & Company
By Google News Motors ·
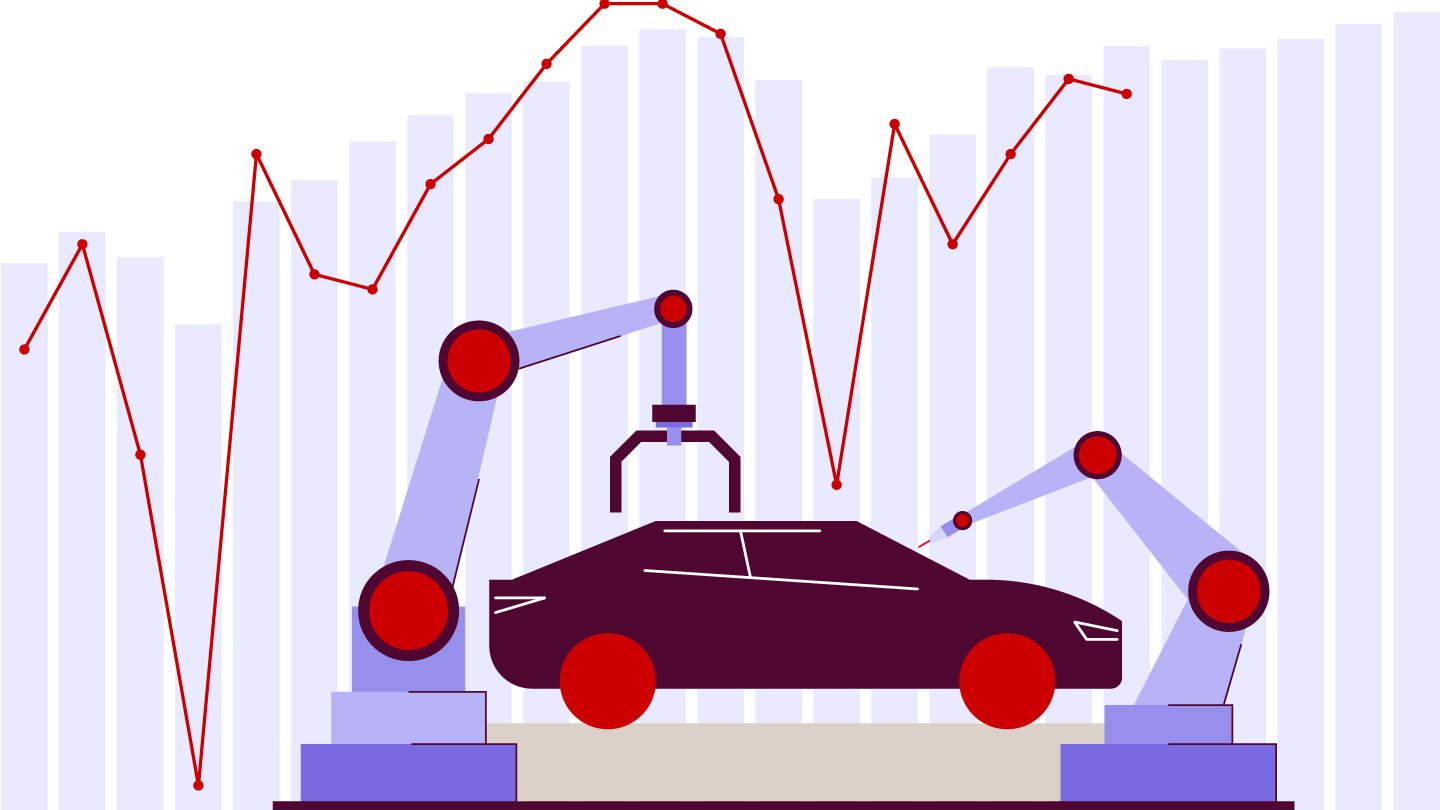
Notes: 2008–19 EBITDA margins based on top 100 automotive suppliers of 2015; 2020–25 EBITDA margins based on top 100 automotive suppliers of 2025
Auto suppliers have come through two severe shocks in 20 years, and each time rising vehicle production helped them recover, keeping average EBITDA margins around 11%. That help is ending. With production expected to remain flat in mature markets and China, the next downturn will be harder to recover from.
Production volumes rose 45% over the past 20 years, and the industry’s dependence on ever higher output remains a key vulnerability. High fixed costs, capital intensity, and late breakeven points make suppliers particularly sensitive to fluctuations in demand. In the 2008–09 financial crisis, a 16% decline in car production erased a third of industry profitability. In 2020, a 21% drop in production, caused by the pandemic supply crisis, cut profit by more than a quarter.
The strategic challenge for suppliers will be finding new sources of growth in flat markets. Survivors will strengthen cost competitiveness while expanding into new geographies and customer relationships. They will seek a larger share of existing customers’ spending, increase content per vehicle, and explore adjacent markets such as robotics and defense.
Winners will go further. They will reshape their portfolios to ensure that businesses selling commoditized products achieve the scale needed to compete on cost, while innovation-led businesses receive the management focus and funding to outrun competition on technology and speed. In a market where volume growth slows or stalls, strategic portfolio choices will increasingly determine which suppliers continue to thrive.
Originally published by Google News Motors