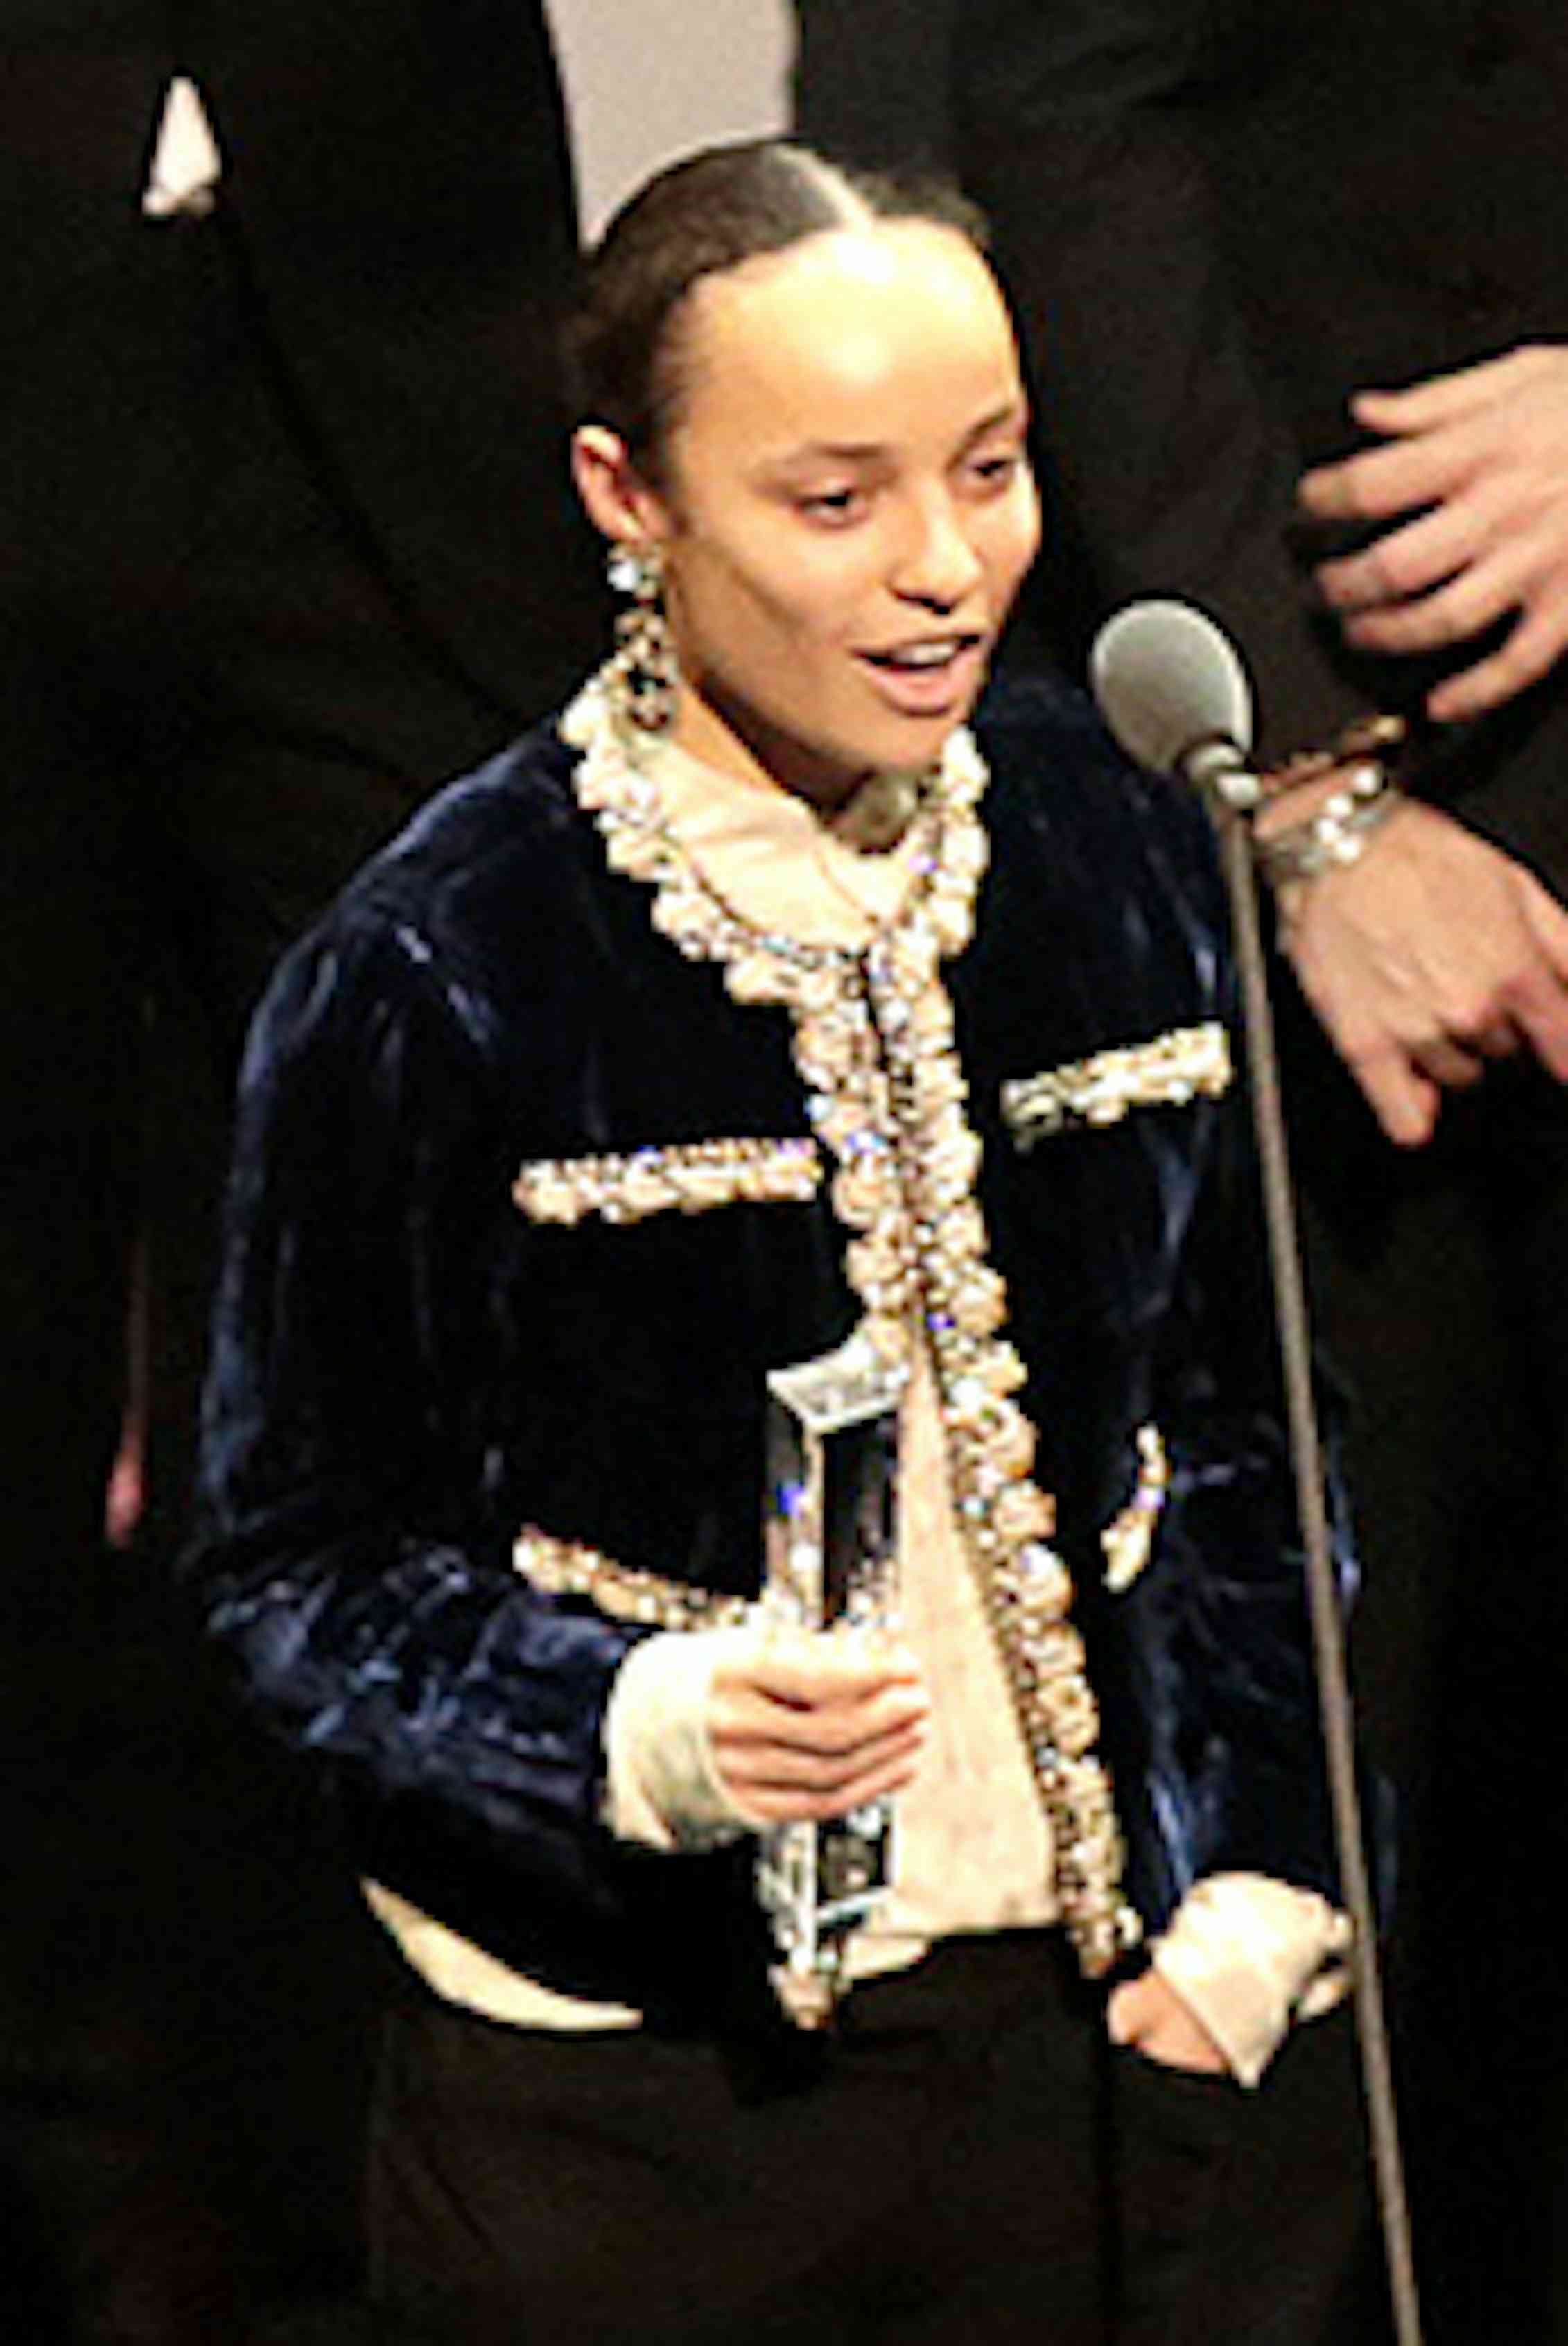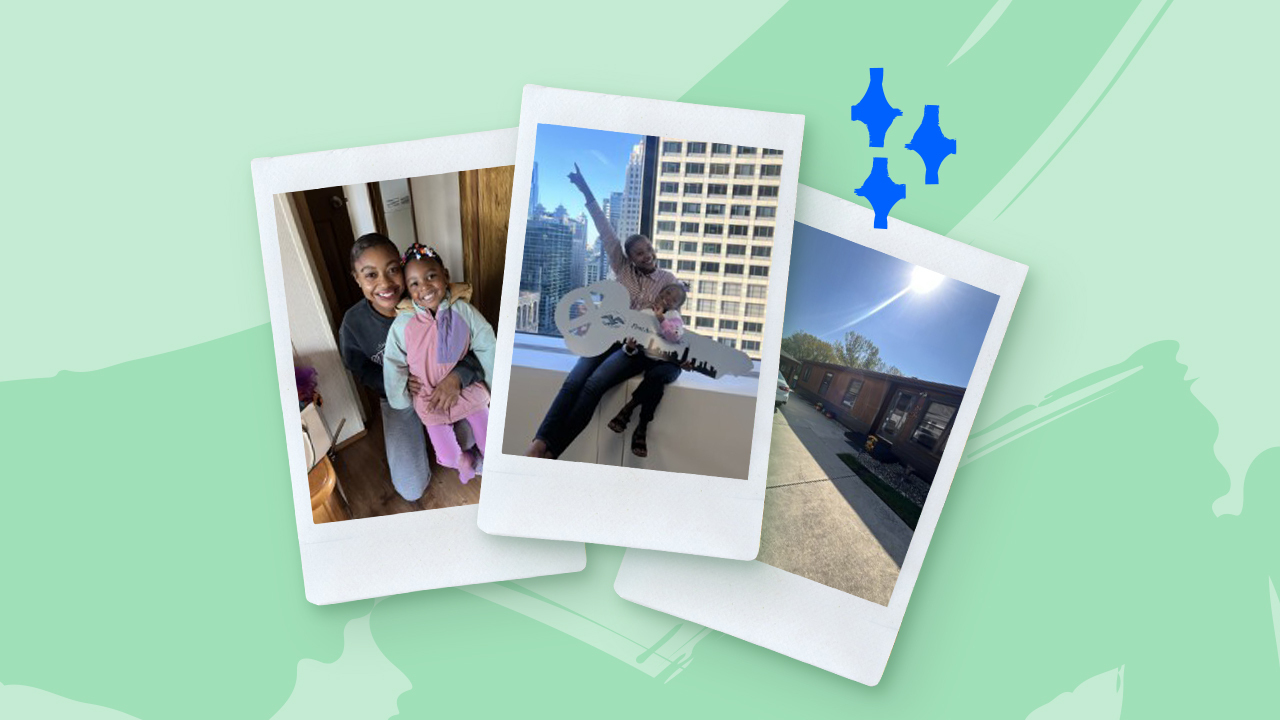
Gabrielle Pickens wasn’t thinking about homeownership until her daughter, Lily, was born in 2021. That moment changed everything. The single Black mother started thinking less about “someday” and more about what kind of stability she could build right now.
That’s when she turned to a benefit she earned during her seven years in the Navy: the VA loan. With competitive interest rates, no down payment requirement, and no private mortgage insurance (PMI), homeownership suddenly felt possible in a way it never had before.
For her, becoming a homeowner was especially meaningful, given her credit challenges and the ongoing struggles she knew Black families can face in accessing homeownership.
“It’s either you’re a victim or a victor in your story,” she says. “What are you going to be?”
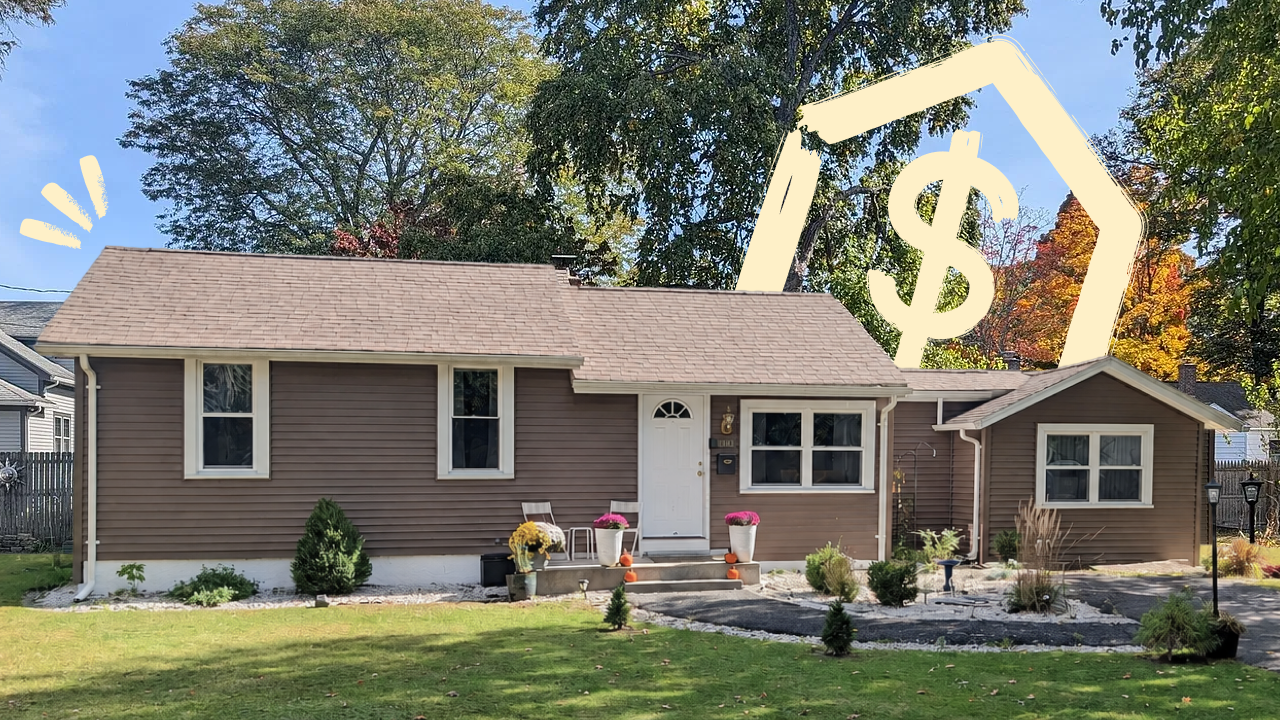
Pickens chose to be a victor. Four years later, after using a VA loan and rebuilding her credit, she stepped into her sunlit, two-bedroom, two-bath home with high ceilings and a spacious yard in the Chicago suburbs.
“I can only control what I do,” Pickens says. “I can’t beat the system of oppression. This is a group project.”
The only thing I can do is make the next logical decision, which is buying the house.
Before Pickens could take advantage of her VA loan benefits, she first had to improve her credit score. At the time, it was in the low 500s.
On average, Black Americans have lower credit scores than white Americans, shaped in part by long-standing gaps in access to wealth-building opportunities. Pickens thought her score would hold her back from homeownership, but her mindset changed when she attended a workshop through the Neighborhood Assistance Corporation of America, a nonprofit housing counseling and community advocacy organization.
Pickens was surprised to meet many other people with credit challenges.
“There are so many ways that we end up with bad credit,” she says. “Nobody wakes up and says, ‘You know what? I’m about to mess my credit up.’ Life happens.”
Working with a housing counselor, Pickens reviewed her finances every few months, paid down debt, corrected errors on her credit report, and built healthier credit habits. The effort paid off. Over roughly 18 months, Pickens increased her credit score from the low 500s to around 720 and saved $12,000 toward her home purchase.
Without the VA loan’s no-down-payment feature, Pickens says she likely would have needed years longer to save enough money to buy a home. The 6.125% interest rate she landed fit comfortably within her budget, and she paid only $2,000 in closing costs. As a disabled veteran, she also qualifies for a property tax exemption that helps keep her monthly housing costs low.
“I love it,” Pickens says. “I’m grateful for my mortgage rate and not being cash-strapped and trying to live above my means. A $1,000 mortgage for a two-bed, two-bath home in the suburbs? I’ll take it.”
Government-backed VA and FHA loans are critical for Black homebuyers because their low thresholds help open the door to homeownership. But as Andre Perry, a senior fellow at the Brookings Institution, a nonprofit public policy organization based in Washington, D.C., stresses, more products such as these are needed to support Black homeownership.
Perry highlights programs with small or no down payment requirements and credit models that consider a person’s rent payment history. He also points to Special Purpose Credit Programs (SPCPs) designed to expand access for historically underserved communities…